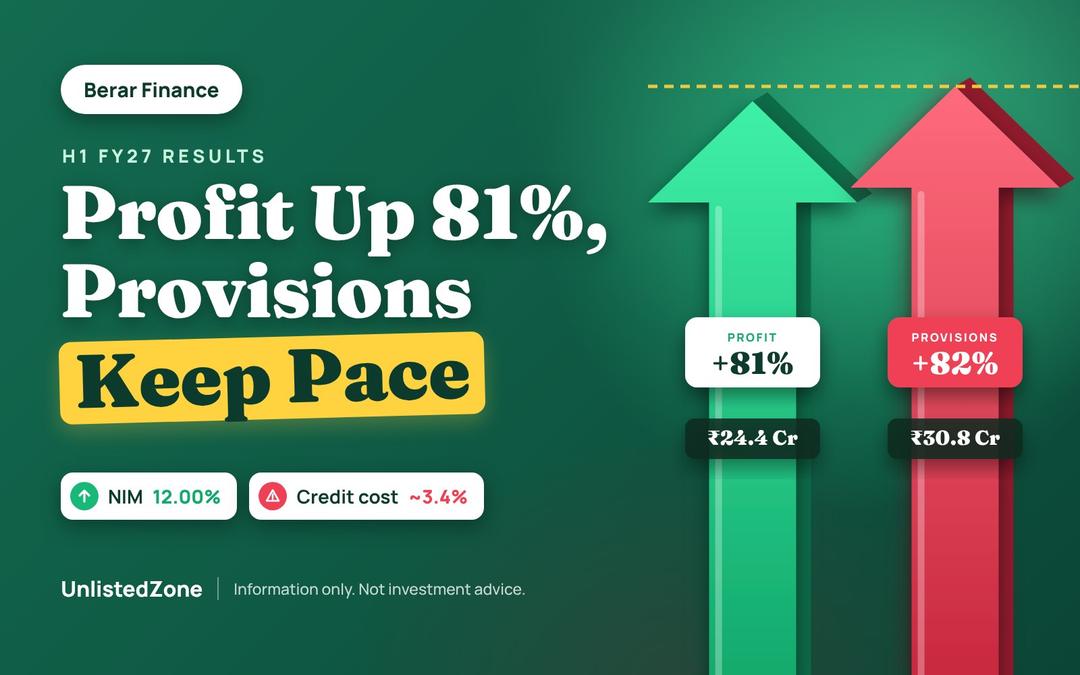
Berar Finance's profit rose 81% to ₹24.4 Cr in H1 FY27 (April–September 2026), from ₹13.4 Cr in H1 FY26. Total income grew 33% to ₹218.9 Cr, and net interest income (NII) grew 48% to ₹109.0 Cr.
H1 profit is already 67% of FY26's full-year profit of ₹36.2 Cr. Provisions also rose 82% to ₹30.8 Cr, the same pace as pre-provision profit, so credit cost remains the main thing to watch.
The Nagpur-based NBFC's board approved these unaudited results on 3 November 2026. The statutory auditors, N.A. Shah Associates LLP, carried out a limited review. All figures below are in ₹ crore unless stated.
Pre-provision operating profit rose 82%, much faster than income, because finance cost and opex grew slower than income.
₹ Cr | H1 FY26 | H1 FY27 | Change |
|---|---|---|---|
| Interest income | 147.8 | 196.7 | +33% |
| Fee & commission income | 10.5 | 13.0 | +23% |
| Other operating and other income | 5.9 | 9.2 | +56% |
| Total income | 164.3 | 218.9 | +33% |
| Finance cost | 74.4 | 87.7 | +18% |
| Net interest income (NII) | 73.4 | 109.0 | +48% |
| Average loan book | 1,382.5 | 1,815.7 | +31% |
| NIM (annualised) | 10.62% | 12.00% | +1.38 pts |
| Employee cost | 36.2 | 48.5 | +34% |
| Other expenses + D&A | 19.3 | 19.9 | +3% |
| Pre-provision operating profit | 34.4 | 62.8 | +82% |
| Provisions (impairment) | 16.9 | 30.8 | +82% |
| Profit before tax | 17.5 | 32.0 | +82% |
| Tax | 4.1 | 7.6 | +84% |
| Profit after tax | 13.4 | 24.4 | +81% |
| EPS, basic (₹, not annualised) | 10.89 | 16.66 | +53% |
| Net profit margin | 8.18% | 11.13% | +2.95 pts |
NII = interest income less finance cost. Average loan book = average of opening and closing loans for the half year (H1 FY26: Mar-25 ₹1,349.2 Cr and Sep-25 ₹1,415.8 Cr; H1 FY27: Mar-26 ₹1,749.3 Cr and Sep-26 ₹1,882.1 Cr). NIM = NII × 2 ÷ average loan book. Pre-provision operating profit = total income less finance cost, employee cost, other expenses and D&A. EPS grew slower than PAT because the share count rose from 1.23 Cr to 1.45 Cr after the capital raise.
NII grew 48% because interest income (+33%) rose much faster than finance cost (+18%). Borrowing costs grew slower than lending income, so NIM on the average loan book rose to 12.00% from 10.62%. NII grew faster than the average loan book (+31%).
Fee income grew 23% to ₹13.0 Cr, slower than interest income.
Other operating income rose 56% to ₹9.1 Cr. The results do not explain this line, so it may not repeat at the same level.
Costs are more efficient. Opex was 52.1% of net income (total income less finance cost), down from 61.7% in H1 FY26.
Employee cost grew 34% to ₹48.5 Cr and is the largest cost after interest. Other expenses and D&A were nearly flat (+3%).
Provisions of ₹30.8 Cr took 49.1% of pre-provision profit in H1 FY27, the same share as in H1 FY26. Profit growth therefore came from the core lending business, not from lower credit costs.
Asset quality | Sep-25 | Mar-26 | Sep-26 |
|---|---|---|---|
| Gross NPA (Stage 3) | 4.52% | 3.72% | 3.80% |
| Net NPA | 2.94% | 2.32% | 2.30% |
| Provision coverage (Stage 3) | 35.91% | 38.60% | 40.49% |
| Half-year provisions (₹ Cr) | 16.9 | 24.5 | 30.8 |
Half-year provisions for Mar-26 are for H2 FY26 (FY26 ₹41.4 Cr less H1 FY26 ₹16.9 Cr).
NPAs are lower than a year ago. Gross NPA fell from 4.52% to 3.80%, but it is slightly above the 3.72% of March 2026.
Coverage is rising. Provisions now cover 40.5% of Stage 3 loans, up from 35.9% a year ago. Part of the higher provisions went into this cushion.
Credit cost is high. H1 provisions equal about 3.4% of the average loan book on an annualised basis.
The company says its Ind AS provisions exceed what RBI's IRACP norms require, so no impairment reserve was needed.
The loan book grew 7.6% in six months to ₹1,882 Cr. Capital stays comfortable at 21.7% CAR, though it has fallen from 25.1% in March as lending grew.
₹ Cr | Mar-26 | Sep-26 | Change |
|---|---|---|---|
| Loans | 1,749.3 | 1,882.1 | +7.6% |
| Cash and bank balances | 164.4 | 250.5 | +52% |
| Total assets | 2,035.8 | 2,328.8 | +14% |
| Debt securities (NCDs) | 195.4 | 238.8 | +22% |
| Bank and other borrowings | 1,152.9 | 1,389.3 | +21% |
| Deposits | 135.4 | 127.0 | −6% |
| Total borrowings | 1,483.7 | 1,755.1 | +18% |
| Net worth | 498.6 | 521.7 | +5% |
Ratio | Sep-25 | Mar-26 | Sep-26 |
|---|---|---|---|
| Capital adequacy (CAR) | 20.51% | 25.09% | 21.74% |
| Debt to equity | 4.14x | 2.98x | 3.37x |
| Debt to total assets | 78.54% | 72.90% | 75.45% |
| Net worth (₹ Cr) | 339.6 | 498.6 | 521.7 |
Net worth is up 54% from ₹340 Cr a year ago. Most of the increase came from new equity raised between September 2025 and March 2026; paid-up capital rose from ₹12.3 Cr to ₹14.5 Cr.
Leverage is rising again. Debt to equity went from 2.98x in March to 3.37x, because borrowings grew faster than net worth.
The cash pile is partly new NCD money. The company raised ₹50 Cr through NCDs on 30 September 2026, and none of it had been used by the quarter end.
The core lending engine is working: NII and pre-provision profit grew far faster than income in H1. Credit cost decides how much of that reaches profit.
Provisions in H2 FY27. H1 provisions of ₹30.8 Cr were already 74% of FY26's full-year ₹41.4 Cr.
Gross NPA trend. It is down from 4.52% a year ago but has edged up from 3.72% in March to 3.80%.
Full-year profit. H1 profit of ₹24.4 Cr is 67% of FY26's ₹36.2 Cr.
Leverage and capital. CAR has fallen from 25.1% to 21.7% in six months; growth at this pace may need fresh capital.
Berar Finance Ltd, unaudited financial results for the quarter and half year ended 30 September 2026, with Regulation 52(4) disclosures and the NCD utilisation statement. Approved by the board on 3 November 2026; limited review by N.A. Shah Associates LLP. Figures converted from ₹ lakh to ₹ crore; NII, pre-provision profit and cost ratios are our calculations.
Information only. Not investment advice.